It’s the question I get asked more than any other right now.
“Haley, should I buy in Melbourne ‐ or look regional?”
Honest answer? It depends.
Not on what feels right. Not on what the headlines are saying.
But on your goals, your budget, your time horizon ‐ and most importantly, the fundamentals of the asset you’re actually buying.
Because you can do really well in either market. And you can lose money in either market.
The difference is rarely Melbourne vs regional Victoria. It’s almost always about the asset you choose within that market.
Quick Summary: Melbourne vs Regional Victoria
For readers who want the short version:
- Melbourne generally suits buyers prioritising long-term capital growth, with a larger budget and a longer time horizon (10+ years).
- Regional Victoria used to be the cashflow play. In 2026, in the established markets I buy in, that’s no longer the real story.
- The yield gap is still a consideration ‐ 4‐5% regional VIC vs 3‐3.9% Melbourne.
- But the regional case isn’t “more yield” anymore. It’s demand quality, supply constraint and growth. Geelong, in particular, is a city in its own right, priced like one, and performing like one.
- The biggest mistake in either market is buying without understanding the local supply, demand and demographic drivers.
- And as always: the city-vs-regional question matters far less than the specific pocket you pick within either.
The rest of this article walks through when each market makes sense, where buyers go wrong, and the questions to ask yourself before deciding.
Why this question matters more than ever in 2026
A few things have shifted in the last five years.
- Remote and hybrid work is now permanent for many professionals.
- Regional Victoria saw significant population inflow during and after COVID.
- Melbourne’s median house price has, over the long term, continued to rise faster than wages.
- Regional yields have looked more attractive on paper.
- State and federal infrastructure spending has lifted parts of regional Victoria.
Combined with rising interest rates and tighter borrowing capacity?
Many buyers who would have automatically purchased in Melbourne five years ago are now seriously considering regional options.
That’s not necessarily a bad thing. But it does mean the decision needs to be made on fundamentals, not on the feeling of “getting more for your money.”
Because in property, getting more on day one doesn’t always mean getting more over a decade.
Melbourne vs Regional Victoria: Key Differences at a Glance
For readers who want the side-by-side comparison:
- Capital growth: Melbourne has typically been stronger over a 10‐20 year horizon, but the best regional pockets have matched or beaten it. More on that below.
- Rental yield: Regional Victoria typically delivers higher gross yields (often 4‐5%+ vs ~3.0‐3.9% in Melbourne).
- Entry price: Regional Victoria offers a lower entry point in most cases ‐ but not always where you’d expect. Core Geelong is priced like Melbourne’s middle ring.
- Risk profile: Melbourne is generally more stable; regional markets can be more variable.
- Liquidity: Melbourne has materially higher transaction volume and a deeper buyer pool.
- Demand drivers: Melbourne benefits from diversified employment; regional markets often rely on a smaller set of economic drivers. But some suburbs in Geelong and Ballarat, for example, have greater economic diversity than some Melbourne suburbs.
These are generalisations ‐ and like all generalisations, they break down at the suburb and asset level. But as a starting frame for the decision, they’re a useful baseline.
The case for buying in Melbourne
Melbourne remains one of the most diversified, deepest property markets in Australia.
Deep matters. It means:
- Multiple buyer pools.
- Strong long-term population growth.
- Employment spread across many industries, not one.
- Higher transaction volume = better liquidity when you sell.
- Established infrastructure across rail, road, health and education.
Take Hoppers Crossing in the west. Typical house around $756,000, renting at roughly $473 a week ‐ a gross yield near 3.3%. It’s grown about 70% over the past ten years, on a market turning over close to 900 house sales a year (HTAG Intelligence, data to June 2026).
That last number is the quiet hero. ~900 sales a year means liquidity. It means when you sell, there’s a queue.
You can read the full breakdown in our Hoppers Crossing property investment analysis.
But ‐ and this matters ‐ not every Melbourne suburb works. The same fundamentals that make Melbourne strong overall can be completely missing two suburbs over. I cover that in Melbourne suburbs to avoid.
The case for buying in regional Victoria ‐ and why I’m loving Geelong right now
Regional Victoria is no longer the afterthought it was a decade ago.
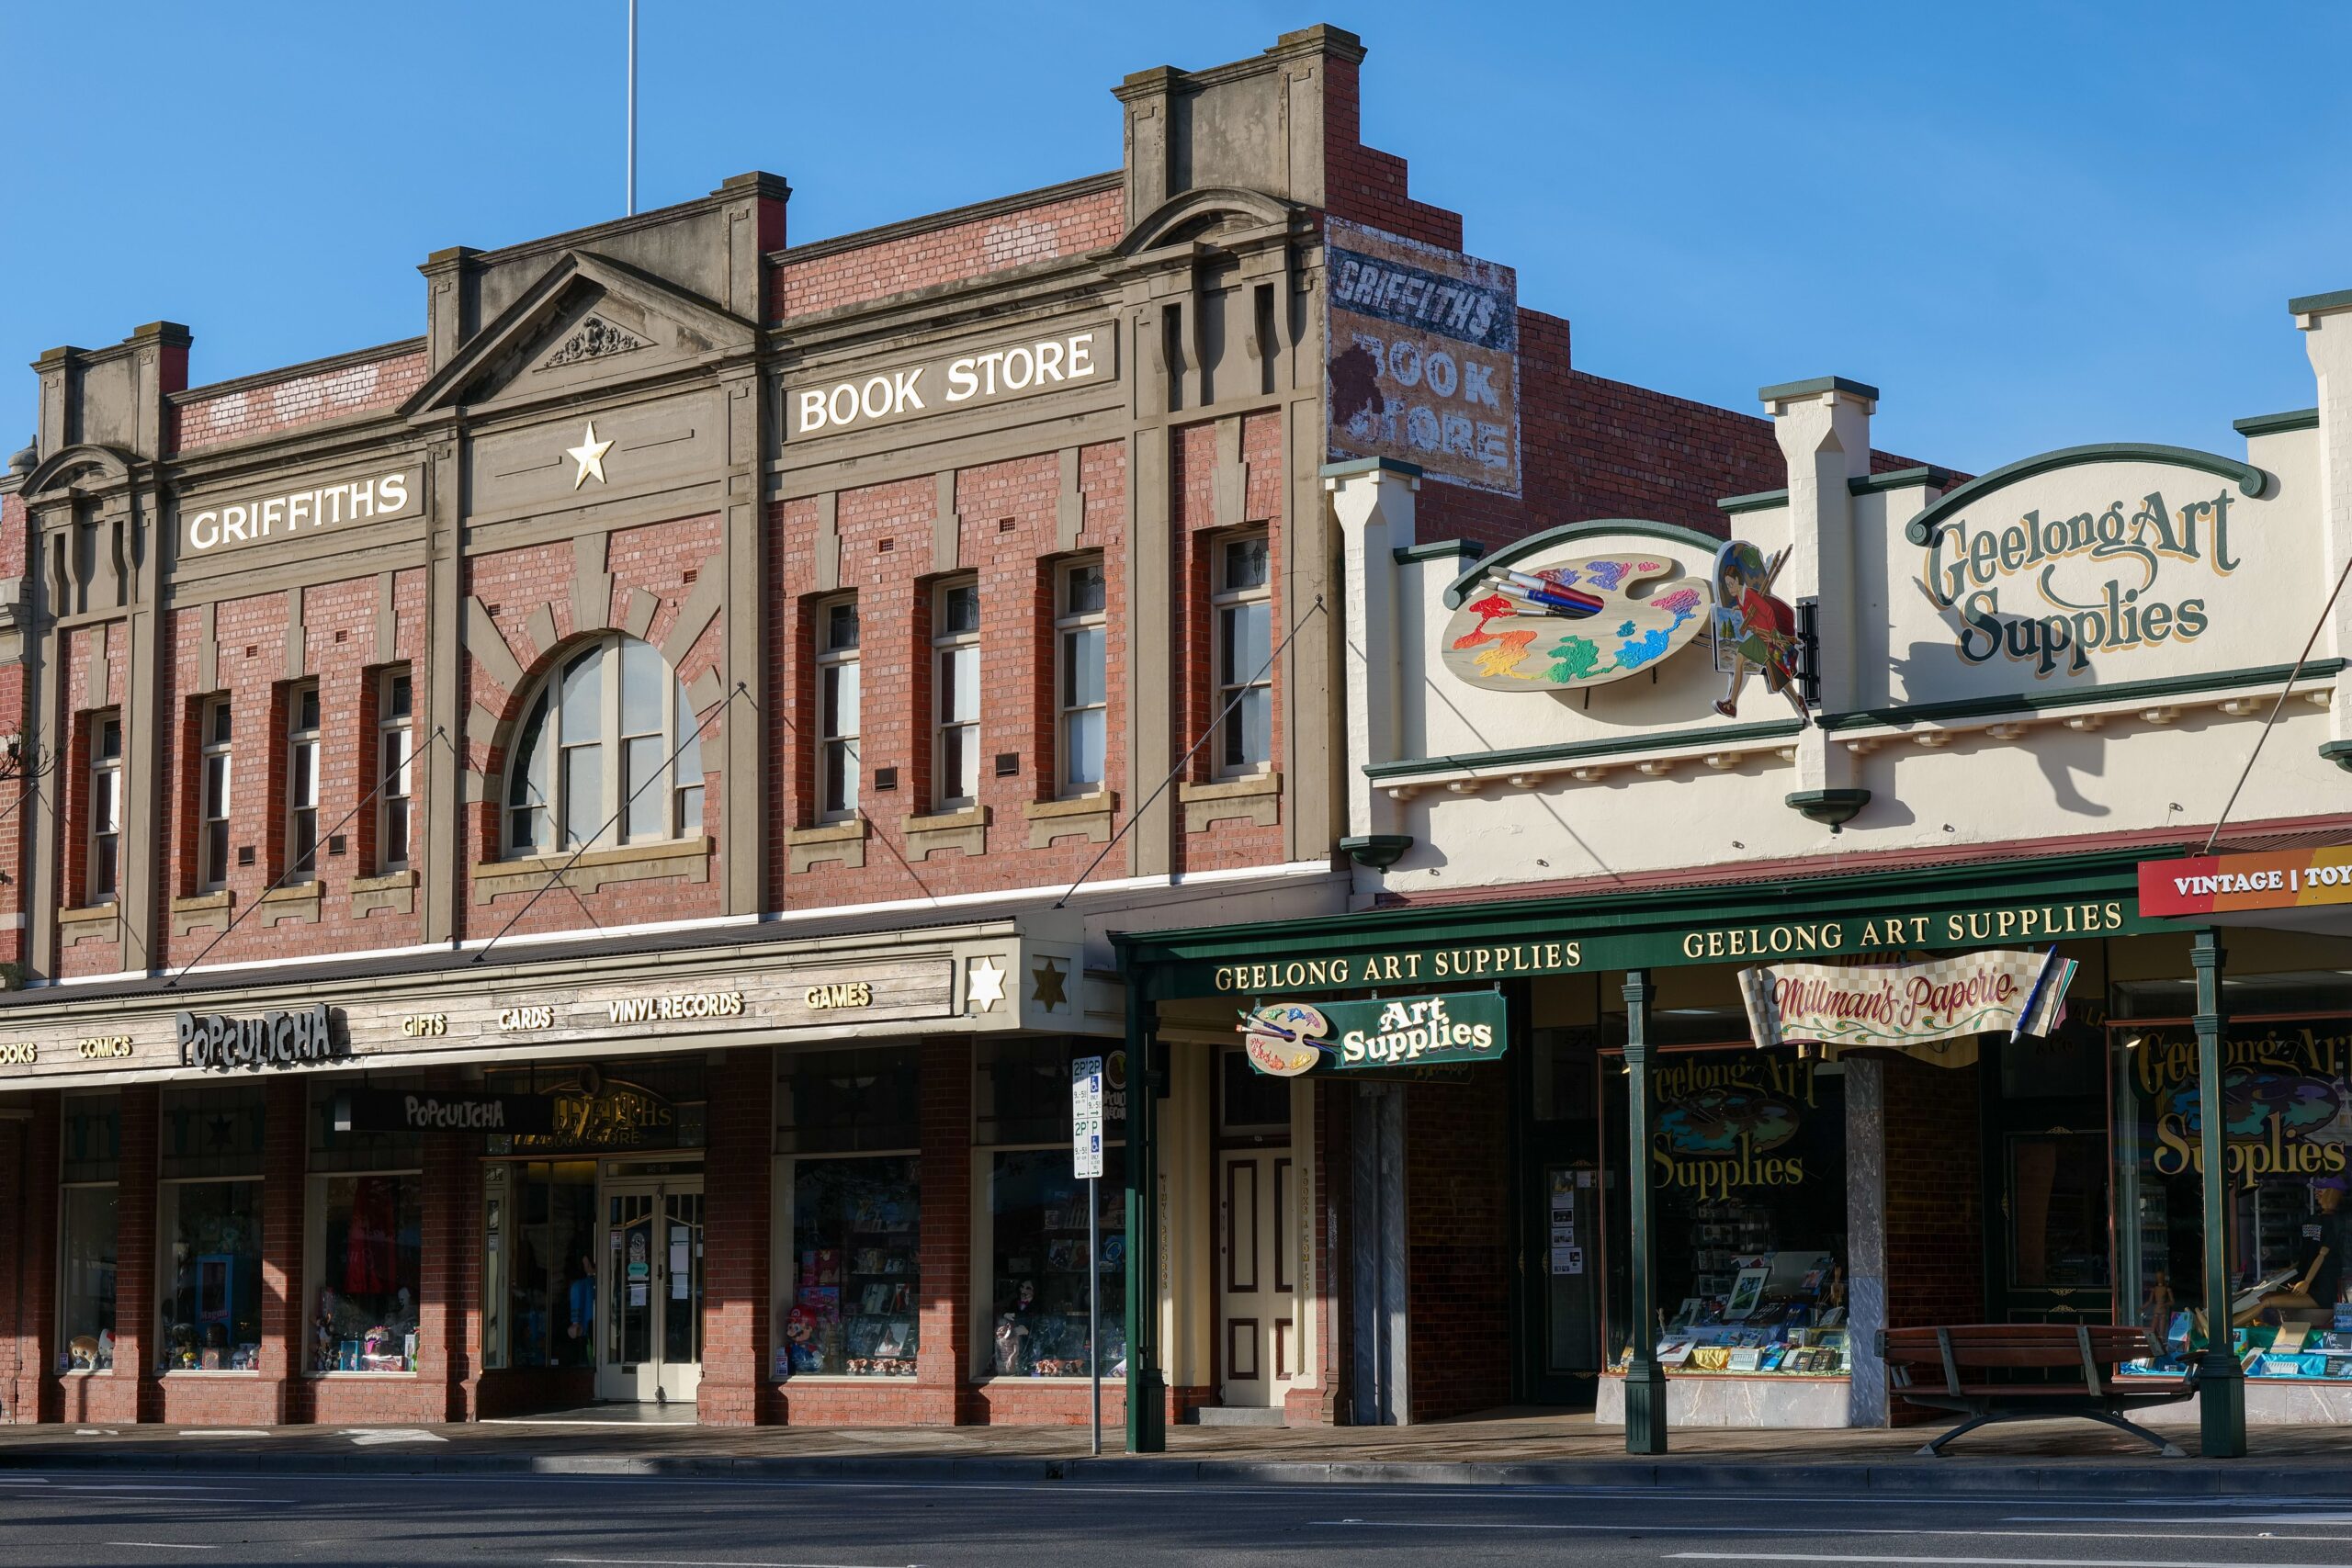
Geelong, Ballarat and Bendigo are real economies now. Geelong alone is home to nearly 300,000 people, with a diversified base across health, education, advanced manufacturing and government.
These aren’t sleepy country towns. They’re cities. And in their established pockets, they behave like cities.
Here’s where it gets interesting ‐ and where the spreadsheet wisdom falls apart.
Grovedale, Geelong. Typical house around $728,000. Renting at roughly $522 a week ‐ a gross yield near 3.7%. Up about 14% in the past year alone, and 101% over the past ten years (source: HTAG Intelligence, data to June 2026).
Read that again.
Cheaper entry than Hoppers Crossing. Higher rent. Better yield. And it’s out-grown comparable Melbourne over a decade.
Belmont, just next door, tells the same story ‐ ~$798k typical, 3.4% yield, 83% growth over ten years.
This is not “Melbourne for less money.” It’s a different market doing its own thing ‐ and doing it well.
What regional Victoria offers
- Lower entry prices ($500‐700k buys a quality established home).
- Higher gross rental yields in some regional markets (4‐5%+, depending on the centre and asset).
- Specific macro drivers tied to infrastructure investment.
- Less competition from foreign and institutional buyers in some markets.
- Strong owner-occupier demand in the right pockets.
The $655M expansion of Ballarat Base Hospital, for example, isn’t just a hospital upgrade.
It creates jobs. It draws health professionals into the region. It increases housing demand ‐ both rental and owner-occupier.
That’s the kind of macro driver that moves regional markets meaningfully over a 5‐10 year horizon.
Regional is generally the stronger choice when:
- You want to diversify and spread risk across multiple properties.
- You want higher yields to support a larger portfolio.
- You’re comfortable researching demographic and employment fundamentals carefully.
- You can identify regional centres with diversified, growing economies ‐ not single-industry towns.
Regional Victoria is not “Melbourne for less money.” It’s a different market with different fundamentals. The buyers who do well there treat it as such.
Where regional Victoria buyers most commonly go wrong
I’ll be honest ‐ this is where I see most regional mistakes.
1. Chasing yield in single-employer towns
A 7% gross yield looks incredible on a spreadsheet ‐ until you learn the town runs on one mine, one factory, one government contract. When that employer pulls back, vacancy spikes, rents drop, values fall, and you can’t sell. The yield isn’t real if the demand isn’t durable. I don’t touch single-industry towns for exactly this reason.
2. Buying in tourist towns at the wrong time of cycle
Coastal short-stay returns can look great. They’re also volatile and seasonal. Investment-grade demand is year-round. Holiday memories are a terrible buying signal.
3. Confusing “cheap” with “value”
A $400k house in a shrinking regional town isn’t a bargain. It’s a slow underperformer with low optionality. Cheap is not the same as undervalued. Undervalued means strong fundamentals that the market hasn’t fully priced in yet. Cheap usually means the market has already worked out there’s a reason the price is low.
4. Ignoring population trends
The centres worth buying in are growing. A quick look at ABS population data and council planning documents tells you which side of the line a town sits on.
Where Melbourne buyers most commonly go wrong
The flip side.
1. Overpaying in “blue chip” inner suburbs at peak
The most familiar suburbs are not always the best investments. Buyers stretch their budget to buy in suburbs they know ‐ often paying a premium that takes years to grow into.
2. Off-the-plan apartments
Oversupply, low land content, weak resale. The decade of data here is, frankly, not pretty. (More in our suburbs-to-avoid piece.)
3. Outer growth corridors with continuous land supply
When developers can keep releasing estates, scarcity never sets in, and growth stays muted. You’re competing with “brand new” forever.
4. Treating Melbourne as one market
Melbourne isn’t one market. It’s hundreds of micro-markets. A property in one pocket can compound at twice the rate of a property two suburbs over. Generic “Melbourne is growing” thinking misses this entirely.
A real side-by-side: Melbourne, Geelong and Bendigo
Forget hypotheticals. Three real suburbs, three rungs of the same ladder, live data (HTAG Intelligence, data to June 2026):
| Metric | Hoppers Crossing (Melbourne) | Grovedale (Geelong) | Kangaroo Flat (Bendigo) |
|---|---|---|---|
| Typical house | ~$756,000 | ~$728,000 | ~$610,000 |
| Rent per week | ~$473 | ~$522 | ~$508 |
| Gross yield | 3.3% | 3.7% | 4.3% |
| 10-year growth | ~70% | ~101% | ~111% |
Watch what happens as you move across. The entry price falls. The yield climbs. And the ten-year growth holds ‐ or improves.
This is where the “trade growth for yield” rule of thumb quietly breaks. Bendigo’s Kangaroo Flat is the cheapest to buy into, the strongest on yield, and the best grower over a decade. On paper, it wins on three fronts.
So why isn’t everyone just buying Bendigo?
Bendigo is further from Melbourne and a smaller city than Geelong, which narrows the buyer base. Geelong sits in the middle: close to a Melbourne-grade market on depth, with growth that’s beaten the comparable Melbourne suburb.
There’s no single winner here. There’s the rung that fits your brief ‐ capital growth and liquidity (Melbourne), city-grade growth at a slight discount (Geelong), or cheaper entry and real cashflow (Bendigo).
The point was never the postcode. It’s that disciplined asset selection wins ‐ on whichever rung you choose.
A decision framework: ask yourself these
Forget the headlines. Forget what the agent told you on the weekend. Sit with these.
1. What is my primary goal ‐ capital growth or rental yield?
If growth: Melbourne or one of the stronger regional centres like Geelong with proven long-term performance. If yield: regional Victoria, but with a careful eye on demand fundamentals.
2. What is my time horizon?
Under 5 years: be cautious anywhere. Property isn’t a short-term asset. 5‐10 years: the right regional pocket can work beautifully. 10+ years: both can perform ‐ pick on fundamentals, not postcode.
3. What is my realistic budget?
Under $700k: you’ll find better-quality stock in regional centres than in Melbourne. $700k‐$1M: solid Melbourne and core Geelong both open up ‐ now it’s strategic.
4. Local knowledge ‐ or access to someone who does?
This matters more in regional markets than Melbourne. Why? Because regional markets are smaller, less liquid, and less forgiving of getting the pocket wrong.
5. Buying for you, or for the market?
Owner-occupiers buy with the heart ‐ fair enough, you live there. Investors can’t afford to. The biggest mistake I see is an investor buying with an owner-occupier’s heart in a location that doesn’t stack up.
6. Risk tolerance?
Melbourne, in established pockets, is generally lower risk. Regional Victoria can be higher risk and higher reward ‐ but only when paired with strong research and disciplined location selection. If you’re risk-averse and prioritising stability, default to Melbourne or large regional like Geelong. If you’re willing to do deeper homework on local employment, infrastructure and demographics, regional can outperform.
Frequently Asked Questions: Melbourne vs Regional Victoria
Neither is automatically better ‐ it depends on your goals, budget and time horizon. Melbourne typically suits long-term capital growth investors with larger budgets. Whilst regional Victoria historically suited cashflow-focused investors with more modest budgets, the strongest regional centres ‐ Geelong especially ‐ can match or beat Melbourne on growth right now. Both markets contain strong and weak pockets, so asset selection within the chosen market matters.
The largest and most diversified regional centres ‐ Geelong, Ballarat and Bendigo ‐ are generally considered the strongest options for property investors due to their diversified economies, ongoing infrastructure investment, and steady population growth. Geelong stands out in 2026: established pockets like Grovedale and Belmont have delivered strong long-term growth. Smaller towns can also perform well in specific cycles but tend to carry higher concentration risk if they rely on a single industry or employer.
Generally, yes. Regional Victoria typically delivers gross rental yields of 4‐5%+, compared to Melbourne yields that often sit in the 3.0‐3.9% range for houses in established suburbs. However, higher yields don’t automatically mean better total returns ‐ Melbourne’s stronger long-term capital growth often offsets the lower yield over a longer horizon.
In the right pockets it’s done better. Geelong’s Grovedale, for example, has grown around 101% over the past decade ‐ ahead of comparable Melbourne suburbs over the same period (source: HTAG Intelligence, data to June 2026). Performance varies enormously by suburb and asset type, which is why suburb-level data beats broad city-vs-regional generalisations.
Yes, in the right centres and the right pockets. The COVID-era surge in regional Victoria has normalised, but the underlying drivers ‐ population inflow, remote work flexibility, and infrastructure investment in centres like Geelong, Ballarat and Bendigo ‐ remain in place. The opportunity requires disciplined asset selection: choosing established pockets in diversified regional centres rather than fringe locations or single-industry towns.
It can be ‐ regional markets are smaller, less liquid and more sensitive to local employment shifts. But buying well in a diversified centre like Geelong can be lower risk than buying poorly in Melbourne. Buying in a single-industry or shrinking town carries materially higher risk.
For many first home buyers, regional Victoria offers an easier path to ownership ‐ lower entry prices, smaller deposits and access to first home buyer concessions. The trade-off is commute distance and access to employment. First home buyers should consider whether the property aligns with their personal goals (where they want to live, work and raise a family) as well as its long-term value.
Significantly. Major projects like the West Gate Tunnel and Melbourne Metro shape demand patterns within Melbourne, while regional investments ‐ the $655 million Ballarat Base Hospital expansion, Avalon Airport upgrades, Geelong’s growing port and health precincts ‐ drive demand in regional centres. Buyers should pay close attention to infrastructure pipelines in both markets when choosing where to buy.
Yes, and many experienced investors do exactly this. A common strategy blends a liquid Melbourne growth asset with a strong regional pocket like Geelong. The key is that each property is investment-grade in its own market ‐ not chosen just to tick a ‘city plus regional’ box.
The bottom line
The Melbourne vs regional Victoria debate is, mostly, the wrong debate.
The right debate is:
- What are my goals?
- What is my budget?
- What is my time horizon?
- And which specific asset ‐ in which specific pocket ‐ best matches those answers?
Because at the end of the day, properties don’t perform because they’re in Melbourne or because they’re in regional Victoria.
They perform because of supply, demand, owner-occupier ratios, scarcity and infrastructure access.
Get those right, and either market can work. Get them wrong, and neither will.
That’s exactly when an independent buyer’s advocate earns their fee ‐ by helping you avoid buying an asset that looks right today but underperforms for the next decade.
You can book a call with First Move Property to talk through your brief.
About the Author: Haley Lim
Haley Lim is the Founder and Managing Director of First Move Property, a passionate property investor, and a trusted Melbourne buyers advocate with deep knowledge of both the metropolitan and regional Victorian property markets.
Before founding First Move Property, Haley was a professional negotiator who held senior corporate leadership roles and led high-stakes commercial negotiations worth billions of dollars across Europe, Australia and New Zealand in the fuel and energy sector.
That background gives her clients a clear edge in today’s property market ‐ combining strategic thinking, calm execution and disciplined negotiation. Today, Haley brings that same approach to every client she represents, helping home buyers and investors navigate Melbourne and regional Victoria with clarity, reduce avoidable risk, and secure properties that align with their long-term goals.
Connect with Haley: LinkedIn | Email: haley@firstmoveproperty.com.au | Phone: 0477 555 783
Disclaimer: This article is general information only and does not constitute legal, financial, taxation or personal investment advice. Property selection should always be based on your individual objectives, budget, borrowing capacity and risk profile. Buyers should obtain independent legal, financial and tax advice before making any property decision. Market conditions, planning controls, infrastructure investment and lending settings can change over time. Any suburb or regional commentary in this article reflects the author’s professional opinion based on publicly available market data and is not a recommendation for or against any specific property purchase.